What is the scope and industry significance of the Gene Silencing Therapeutics Market?
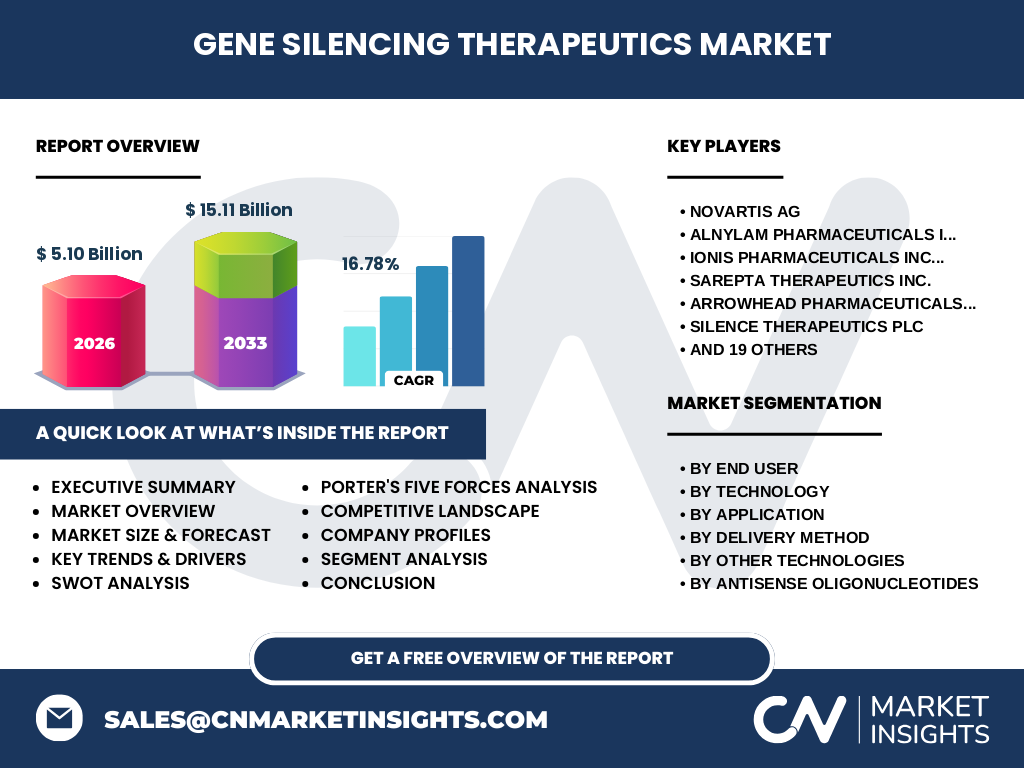
Our proprietary analysis reveals that the Gene Silencing Therapeutics Market size is valued at $5.10 Billion in 2026, establishing a revolutionary paradigm in molecular medicine. This sector focuses on silencing specific disease-causing genes at the mRNA level, offering unprecedented precision for otherwise undruggable targets regulated by strict pharmaceutical GMP standards.
Structural Growth Drivers and Restraints
Key market drivers include surging venture capital investments and robust advancements in delivery vectors such as lipid nanoparticles. However, the Gene Silencing Therapeutics Market industry trends highlight persistent challenges, notably complex intracellular delivery barriers and stringent regulatory oversight by agencies like the FDA and EMA regarding off-target toxicity.
Emerging Trends and Growth Patterns
The transition toward ultra-targeted oligonucleotide chemistry is redefining the Gene Silencing Therapeutics Market analysis. Innovations in peptide-conjugated oligonucleotides and epigenetic silencing technologies are enabling extended dosing intervals, drastically improving patient compliance, and lowering systemic clearance rates.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic initially disrupted clinical trial recruitment and disrupted raw material supply chains for nucleotide synthesis. Nonetheless, the accelerated deployment of lipid nanoparticle platforms during the pandemic catalyzed a major post-crisis recovery, boosting investor confidence across the entire therapeutic pipeline.
Competitive Benchmarking and Market Concentration
The landscape features a blend of pioneering innovators and diversified giants. Market leaders like Alnylam Pharmaceuticals Inc. and Ionis Pharmaceuticals Inc. dominate through robust patent portfolios, while agile players such as Arrowhead Pharmaceuticals Inc. and Silence Therapeutics plc drive specialized delivery breakthroughs.
Executive Summary of Key Findings
Our comprehensive evaluation indicates rapid commercial expansion, underpinned by a forecasted market valuation of $15.11 Billion by 2033. Operating at a robust 16.78% CAGR from 2027 to 2033, the sector is transitioning from rare genetic diseases to high-prevalence oncological and metabolic indications.
Market Forecast from 2027 to 2033
Propelled by scalable manufacturing techniques and expanding clinical pipelines, the market scales efficiently from its 2026 baseline. Our data suggests that accelerated approvals in RNA interference and antisense oligonucleotides will drive exponential revenue acceleration through 2033.
Segmentation Analysis: Technologies and End Users
The market segments by technology into Ribonucleic Acid Interference, Antisense Oligonucleotides, and other advanced mechanisms. End users span Hospitals, Research Institutes, and Pharmaceutical and Biotechnology Companies, with biotech firms acting as the primary engine for early-stage clinical validation.
Geographic Distribution and Regional Performance
North America retains dominant market share, supported by robust venture funding, advanced clinical research infrastructure, and favorable FDA expedited pathways. Meanwhile, Europe and Asia-Pacific exhibit accelerating adoption curves driven by localized government biotechnology funding initiatives.
In-Depth Regional Review
North American growth is anchored by major biotech hubs in Boston and San Francisco, whereas the Asia-Pacific region is rapidly emerging as a preferred destination for cost-effective clinical trials and collaborative manufacturing partnerships involving regional innovators like Sirnaomics Ltd. and OliX Pharmaceuticals Inc.
Strategic Positioning of Leading Companies
Industry participants deploy distinct strategic plays. Novartis AG and Novo Nordisk leverage extensive commercial reach for late-stage acquisitions, while specialized firms like Sarepta Therapeutics Inc. and Stoke Therapeutics Inc. focus intensely on rare neuromuscular and central nervous system disorders.
Porter's Five Forces Analysis
The threat of new entrants is moderate due to high intellectual property barriers and steep R&D capital requirements. Bargaining power of suppliers is low regarding specialized raw materials, whereas competitive rivalry among established platform developers remains intensely high.
SWOT Analysis of the Sector
Strengths include high target specificity and durable therapeutic effects. Weaknesses involve complex delivery vehicle stability. Opportunities lie in expanding into prevalent cardiometabolic diseases, while threats center on potential patent cliffs and stringent regulatory pricing pressures.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with custom phosphoramidite raw material synthesis, progressing through advanced bioconjugation and nanoparticle formulation, and culminating in clinical administration across specialized hospital units and research institutes for oncology and genetic disorders.
Investment Insights and High-Potential Areas
High-potential investment corridors center on proprietary non-viral delivery platforms and tissue-specific targeting ligands. Investors should prioritize clinical-stage firms developing advanced gapmer antisense oligonucleotides and microRNA therapeutics with validated safety profiles.
Conclusion and Strategic Takeaways
The trajectory underscores an irreversible shift toward precision genetic medicine. Sustained investments in novel delivery systems and biomarker identification will separate market leaders from laggards as the sector marches toward its 2033 valuation milestone.
Research Methodology and Baseline Triangulation
Our findings are derived by triangulating primary executive interviews with key opinion leaders, secondary macroeconomic indicators, regulatory submission registries, and proprietary trade database metrics to establish rigorous baseline estimates and accurate forward projections.
Scope of the Report and Coverage Parameters
This report encompasses a comprehensive global assessment of the Gene Silencing Therapeutics Market, analyzing therapeutic modalities, delivery mechanisms, applications, and geographic performance from 2026 through 2033, while explicitly detailing methodological constraints and macro risk factors.
Recent Developments and Strategic Industry Moves
Recent milestones feature active licensing agreements, clinical trial expansions by firms like Arbutus Biopharma Corporation and PepGen Inc., and regulatory clearances for novel nanoparticle-delivered RNAi therapies, reinforcing ongoing confidence in commercial scalability.